What makes an ESCO different?
The 2011 study treats performance-based contracting as the common thread in energy service companies: payment connects to energy savings. It also records that the ESCO label was used differently across markets. Auditing, selling equipment and delivering a guaranteed outcome are distinct capabilities.
That distinction remains a useful due-diligence question. Ask what the provider actually contracts to do, which results it guarantees and what remedy applies if performance falls short. The historical country scores are not a current list of qualified providers.

Read the diagram as text
Baseline: Metered energy + operations → Intervention: Equipment + responsibility → Cash flow: Savings less recurring costs → Verification: Measure and explain changes
A capability ladder, not a popularity contest
The report’s framework progresses from evidence of basic service activity to documented implementation, credible savings delivery and developed performance guarantees. A provider count alone cannot show the scale, finances or quality of the firms counted.
For a particular supplier, request evidence connected to the proposed project: relevant technical experience, completion records, measurement capability, financial capacity, insurance and the proposed allocation of delivery risk. Do not accept unrelated project photographs as proof of guaranteed savings.
Seven questions for a contract review
| Baseline | Which meter records and operating conditions establish the starting point? How are weather, occupancy and production changes handled? |
| Scope | Which equipment and services are included? Who owns the new assets and who authorizes operating changes? |
| Measurement | Who measures performance, at which boundary and frequency? How can either party review the evidence? |
| Savings and payment | Is payment based on physical savings, monetary savings or a defined formula? Who carries tariff movements? |
| Guarantee | What is promised, for how long and with which exclusions? What compensation or correction applies to a shortfall? |
| Operations | Who maintains equipment, pays recurring costs and manages outages or changes in site use? |
| Exit and finance | How do termination, assignment, lender rights and the remaining asset value interact? |
Illustrative baseline dispute
Suppose an office records lower electricity consumption after a retrofit, but occupancy also falls. A raw before-and-after comparison can overstate the intervention’s effect. A defensible review records the change in occupancy and applies the adjustment method agreed in the contract.
Conversely, higher production may conceal an improvement in energy per unit of output. Choose the performance boundary before installation, keep the adjustment rules inspectable and agree how missing data will be resolved. This example explains the review problem; it is not a report of a ReEx customer project.
Prepare the evidence before negotiating price
Use a register with an evidence link, date, responsible party and open question for each contract item. Have the technical and legal reviewers examine the same operating assumptions. A strong guarantee on paper can be weak if the baseline is unresolved or the counterparty cannot perform.
The checklist is explanatory. The suitability and enforceability of an actual agreement depend on its jurisdiction, wording, parties and project evidence.
Sources & further reading
- ESCO definitions and country evidence · page 77
- ESCO capacity decision tree · page 78
- Six-country study reading guide
- Prepare a project evidence package
Source dates and reporting periods apply. External publishers do not endorse this website.
Agree the baseline model before claiming a saving
The existing contract guide explains why changes in occupancy or production can distort a before-and-after comparison. Make that risk concrete with a baseline record and a numerical sensitivity example. Agree the measurement boundary, period and adjustment rule before reviewing savings. A spreadsheet alone does not establish that an intervention caused a change.
Keep the reference and reporting conditions together
Record the meter, the equipment inside the boundary and the period covered. Keep the observed energy beside relevant operating conditions such as output, occupancy or weather. Identify gaps and changes in instruments. A baseline adjustment is an agreed model with limitations, not a free choice of whichever comparison makes the saving larger.
A fictional linear-output example
Assume a teaching reference period uses 100,000 kWh to make 10,000 units. In a reporting period, output falls to 9,000 units and measured energy is 85,000 kWh. A raw subtraction gives 15,000 kWh. For this exercise only, suppose the parties have agreed a purely linear reference model of 10 kWh per unit, with no fixed load.
At 9,000 units, that model predicts 90,000 kWh. The illustrative adjusted difference is therefore 90,000 − 85,000 = 5,000 kWh, not the raw 15,000. The other 10,000 kWh reflects the model’s output adjustment. These inputs are invented; the assumed zero fixed load is not a general industrial rule.
Check a boundary case: if measured energy were 92,000 kWh at the same output, the difference would be −2,000 kWh. Preserve the negative sign rather than reporting a saving. A real model may need a fixed component, weather terms or a non-linear relationship. A small example cannot establish which model is appropriate or its uncertainty.
Ask the reviewer to accept the rule, not just the number
- Identify the meter, interval and operating data sources.
- State the reference model and who agreed it.
- Show reference conditions and reporting conditions side by side.
- Calculate the adjusted reference and measured difference with units.
- Test missing inputs and a negative result; keep them visible.
- Record the responsible reviewer, unresolved assumptions and how a dispute is handled.
Do not multiply an unverified energy difference by a tariff and present it as an established cash saving. Tariffs, recurring costs and payment terms require separate evidence. The downloadable sheet leaves those fields outside this physical comparison. ReEx’s example is education, not a commissioned audit, certified M&V method or a report of a customer result.
IRENA’s historical risk and finance publication supplies broader context on preparing project documentation. For a real performance contract, the technical and legal reviewers must agree the applicable measurement method and the meaning of the savings guarantee.
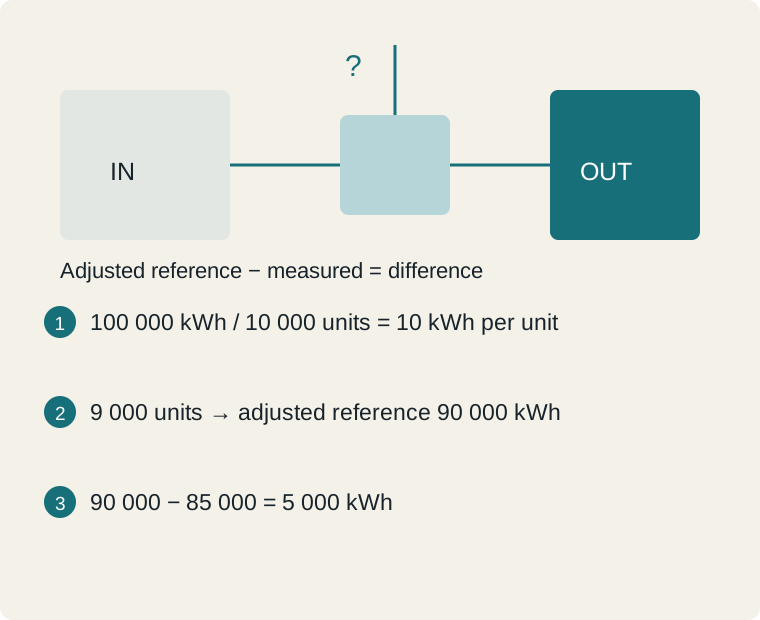
Steps: 100 000 kWh / 10 000 units = 10 kWh per unit → 9 000 units → adjusted reference 90 000 kWh → 90 000 − 85 000 = 5 000 kWh
| Field | Completed example |
|---|---|
| Boundary and period | Fictional process; matched periods |
| Reference energy / output | 100 000 kWh / 10 000 units |
| Agreed model and limitation | 10 kWh per unit; zero fixed load assumed |
| Reporting output / energy | 9 000 units / 85 000 kWh |
| Adjusted reference / difference | 90 000 kWh / 5 000 kWh |
| Reviewer and unresolved assumptions | No real reviewer; model suitability unestablished |
Blank worksheet and worked example ↓
Primary context: IRENA: risk mitigation and structured finance (2016)