The 2012 guide subject has been rebuilt as an original public 2026 resource.
Choose the capital that fits the stage
Early development capital pays for uncertainty: land studies, permits, resource assessment, engineering and commercial development. Construction finance requires much stronger evidence of deliverability and repayment. Operating-asset capital is primarily concerned with the durability of cash flows.
Before adding another stage to the process, compare the evidence list with the due-diligence guide. Use the project contact brief to describe the decision and the missing information, without treating a historic project record as a current mandate.
Show the path between these stages. If the business needs a second raise to reach construction, explain the expected milestone, cost, timing and dilution. Avoid describing a development-stage project as shovel-ready when critical permissions remain open.

Read the diagram as text
Project: Rights · resource · stage → Commercial: Offtake · delivery · costs → Evidence: Model · permits · diligence → Capital: Mandate · terms · closing
Prepare a credible funding request
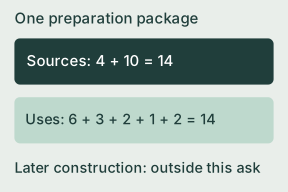
Build a sources-and-uses schedule that reconciles with the model. Separate project expenditure, contingency, transaction costs, debt-service reserves and working capital. State the requested instrument, currency, amount and expected funding date.
Describe the sponsor contribution and how much has already been spent. Explain whether historical development costs are being reimbursed, treated as sponsor equity or excluded. This is often material to the economics of a new investor.
Use an evidence-led pitch
- The need
What customer, system or market problem does the project solve?
- The asset
Where is it, how large is it and what is its development stage?
- The economics
Who pays, under which contract, and what drives operating cash flow?
- The exposure
Which risks remain, who carries them and what evidence supports mitigation?
- The request
What capital is needed, what does it fund and what does the investor receive?
- The next gate
Which decision is requested now and what evidence will be produced next?
Do not confuse interest with readiness
An investor meeting is useful feedback, but it is not a substitute for missing permits or a signed commercial arrangement. Keep a live question log. Mark each issue as resolved, pending evidence or dependent on a future decision.
Run downside cases before outreach. Change resource or demand, tariff, construction cost, operating expense, schedule and currency separately. Then test a combined downside that is internally consistent. Record what would need to change for the project to remain financeable.
Worked preparation example
An efficiency developer wants to finance equipment installations across ten buildings. A useful briefing separates customer contracts from equipment procurement, explains who owns the equipment, describes savings measurement and states what happens if a customer leaves.
Its next step is not simply to list more investors. It may be to standardize the service contract, verify three customer baselines and reconcile installation costs with the deployment schedule. The funding-readiness checklist helps make that next step explicit.
Funding-readiness checklist
Mark only items supported by evidence. This records document coverage, not creditworthiness or funding approval.
Sources & further reading
Source dates and reporting periods apply. External publishers do not endorse this website.
A funded build can still have a cash timing gap
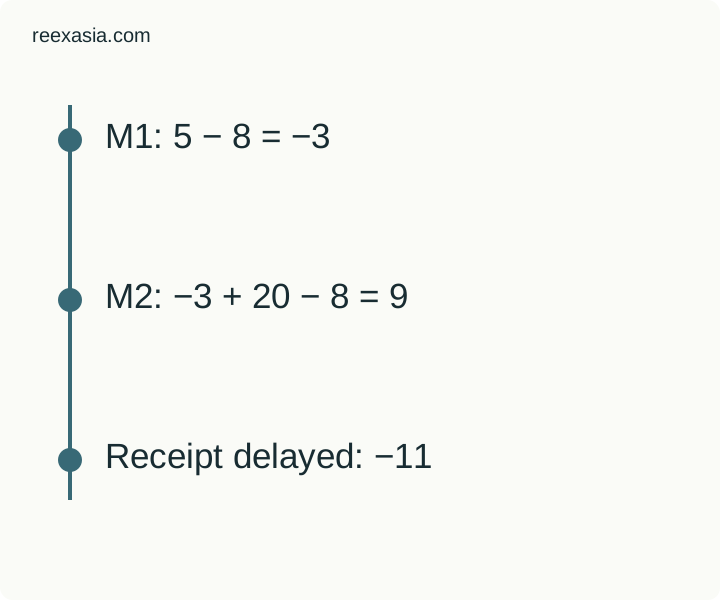
Separate a construction budget from cash available after commissioning. The table is a fictional timing bridge in arbitrary monetary units. It is not a project forecast, financing offer, investment recommendation or evidence of a REEX transaction.
- Choose a period and show opening unrestricted cash. Keep committed funding, undrawn facilities and expected receipts in separate columns; a commitment is not cash already in the operating account.
- Put receipts in the period when they are expected to arrive, not when an invoice is raised. Show operating payments, debt service and restricted reserves separately where relevant. Do not use the same financing twice in a construction total and an opening balance.
- Calculate each closing balance and carry it into the next period. If the balance goes negative, identify the timing assumption and the evidence needed before discussing any remedy with qualified advisers. An annual positive total can conceal an earlier gap.
Worked record
| At commissioning — fictional | Construction costs are fully funded. Unrestricted opening operating cash is only 5 units. |
|---|---|
| Month 1 | 5 opening + 0 receipts − 8 operating payments = −3. The scheduled receipt has not arrived. |
| Month 2 | −3 carried forward + 20 receipts − 8 operating payments = 9. This arithmetic does not make the earlier −3 fundable. |
| Sensitivity | If the 20-unit receipt slips another month, month 2 closes at −11 before month 3 receipts. This is a scenario, not a probability estimate. |
| Evidence request | Opening cash restriction __; invoice/payment terms __; receipt timing evidence __; payment schedule __; minimum balance convention __; funding availability __. |
Agree whether taxes, interest and reserve accounts are inside the model before using it. A negative line flags an unresolved need; it does not establish creditworthiness or a suitable financial product.
Primary sources: World Bank PPP Resource Center: cash-flow questions