Define the transaction first
A project-finance debt raise, an equity round for a development company and the sale of an operating asset are different processes. They attract different investors, need different documents and expose different risks. State precisely what is being financed, who owns it and what the proposed investor receives.
Translate the proposed advisory work into questions for the due-diligence data room. Identify the evidence available now, the gap to be resolved and who would answer it. The capital-raising guide then helps arrange those questions into a process rather than a list of assumed transactions.
For a project company, distinguish construction funding from refinancing an operating asset. For a corporate raise, explain how the funds are divided between development expenditure, working capital and asset investment. Do not blend a project’s cash flows with a parent company’s ambitions without showing the connection.
Explore the components and the decision
- Solar array
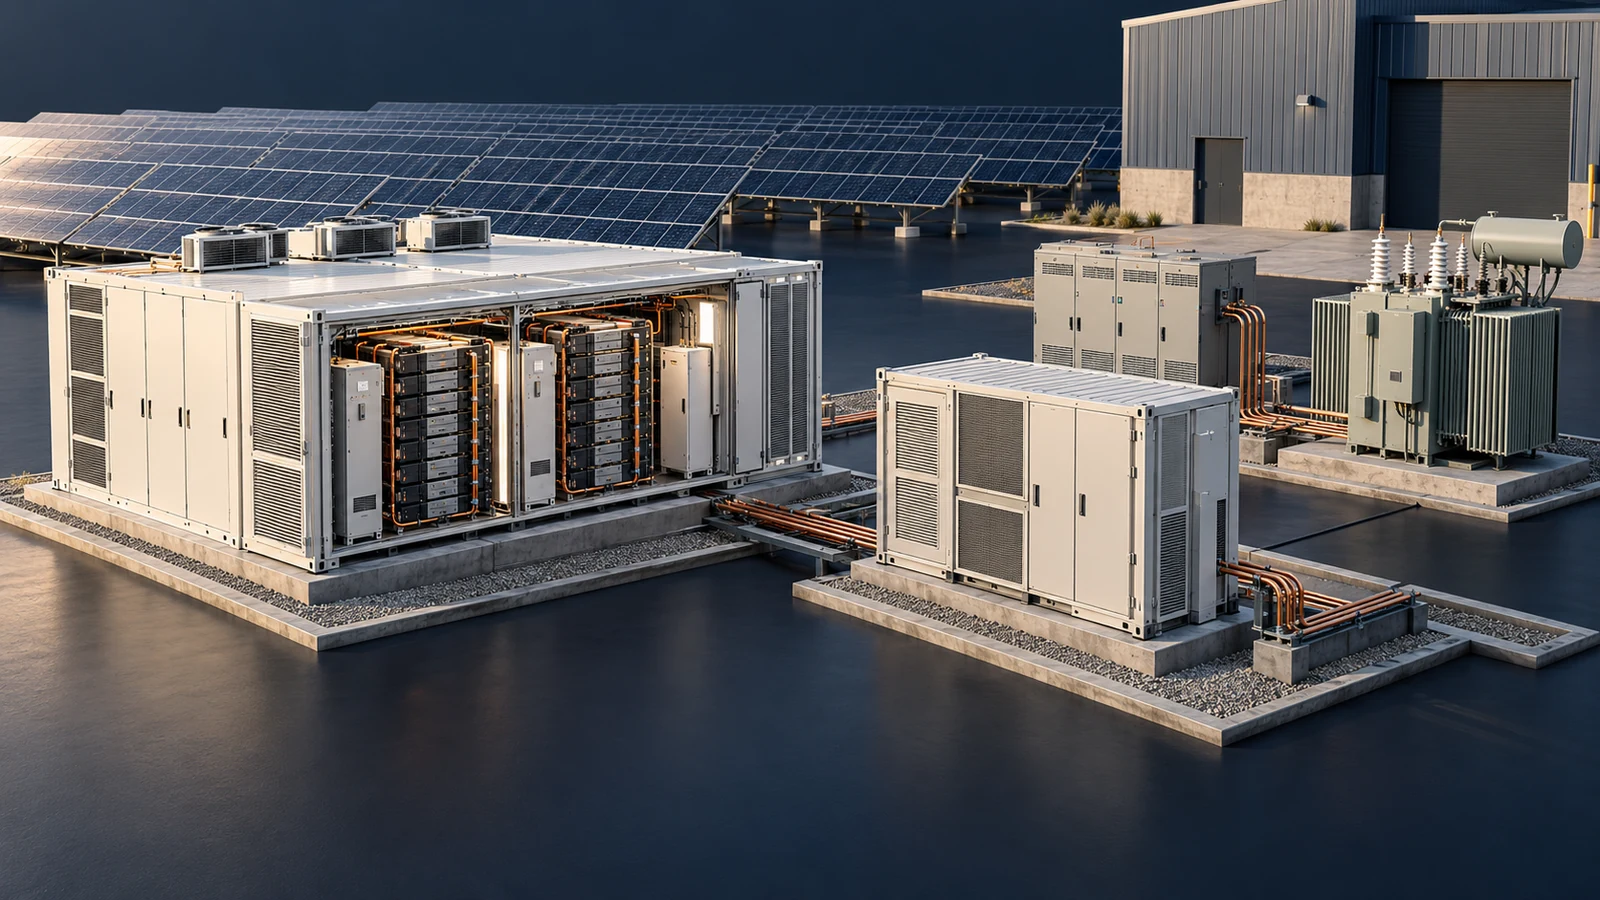
PV modules supply electricity. Energy yield depends on the resource, layout and operating conditions.
- Storage enclosure
Battery racks illustrate stored energy. Capacity, degradation, thermal management and safety require project-specific evidence.
- Power electronics
Inverters and converters manage electrical conversion. The arrangement shown is illustrative; actual AC- or DC-coupled designs differ.
- Grid interface
Switchgear and a transformer represent the connection boundary. Confirm the connection agreement, protection and operating requirements.
Solar resource → electrical conversion → storage or dispatch → connection
DOE: solar systems integration ↗From an idea to a decision.
Five connected questions before a transaction can move forward.
- 01
Project
Define ownership, site rights and the development stage.
- 02
Model
Connect revenue, operating costs and the capital request.
- 03
Evidence
Index contracts, permits, technical studies and open issues.
- 04
Terms
Compare mandates, risk allocation and proposed financing.
- 05
Decision
Resolve conditions and agree the achievable next step.
A workable sell-side sequence
- Prepare the evidence
Build an executive summary, investment memorandum, integrated financial model, ownership chart and indexed data room. Put open issues in a dated register.
- Match the investor mandate
Screen sector, geography, stage, ticket size and instrument. A smaller relevant shortlist is more useful than hundreds of unqualified names.
- Run controlled outreach
Agree what can be shared publicly, under confidentiality and after an indicative offer. Track each question and version of the model.
- Compare offers consistently
Normalize headline valuation, conditions precedent, governance, security, fees and funding certainty. A higher price can carry more execution risk.
- Close the interfaces
Coordinate technical, legal, accounting and environmental reviews. Allocate owners to outstanding conditions and maintain an explicit signing-to-closing schedule.
Buy-side diligence has a different centre of gravity
An acquisition team needs a thesis before a target list: desired geography, technology, operating stage, portfolio role and integration capacity. A long list of assets is not an acquisition strategy.
Reconcile the seller’s model with metered output, actual operating costs, contracts, permits and debt obligations. Identify change-of-control requirements and obligations that survive a sale. Separate issues that change price from those that can prevent closing.
Illustrative document package
| Executive summary | Project, sponsor, location, stage, capital requirement and next decision. |
| Financial model | Transparent inputs, construction schedule, funding sources, taxes, working capital and downside cases. |
| Risk register | Risk, evidence, consequence, mitigation, owner and residual exposure. |
| Process letter | Required offer format, timetable, confidentiality process and evaluation criteria. |
| Data room | Consistent document names, dates, responsible parties and a missing-document log. |
Transaction source references
The April 2012 service page described references including financing for a 66 MW solar project in Thailand, a regional biogas-company sale and a cogeneration-portfolio debt transaction. They are presented separately in our company-history section with their source date. This page does not turn those old references into a current deal pipeline.
Use the project-brief builder to prepare a concise first discussion. If the requested funding amount cannot be tied to a uses-of-funds schedule, resolve that before circulating a teaser.
Common questions
Is a term sheet a funding commitment?
Not necessarily. Review whether the document is binding, its conditions and the steps required before funding.
Should every interested investor get the complete data room?
Use a staged disclosure process that matches confidentiality, mandate fit and transaction progress.
Sources & further reading
- World Bank · Public–private partnership resource centre
- IEA · Southeast Asia Energy Outlook 2026
- ReEx investment-banking page · April 2012
Source dates and reporting periods apply. External publishers do not endorse this website.